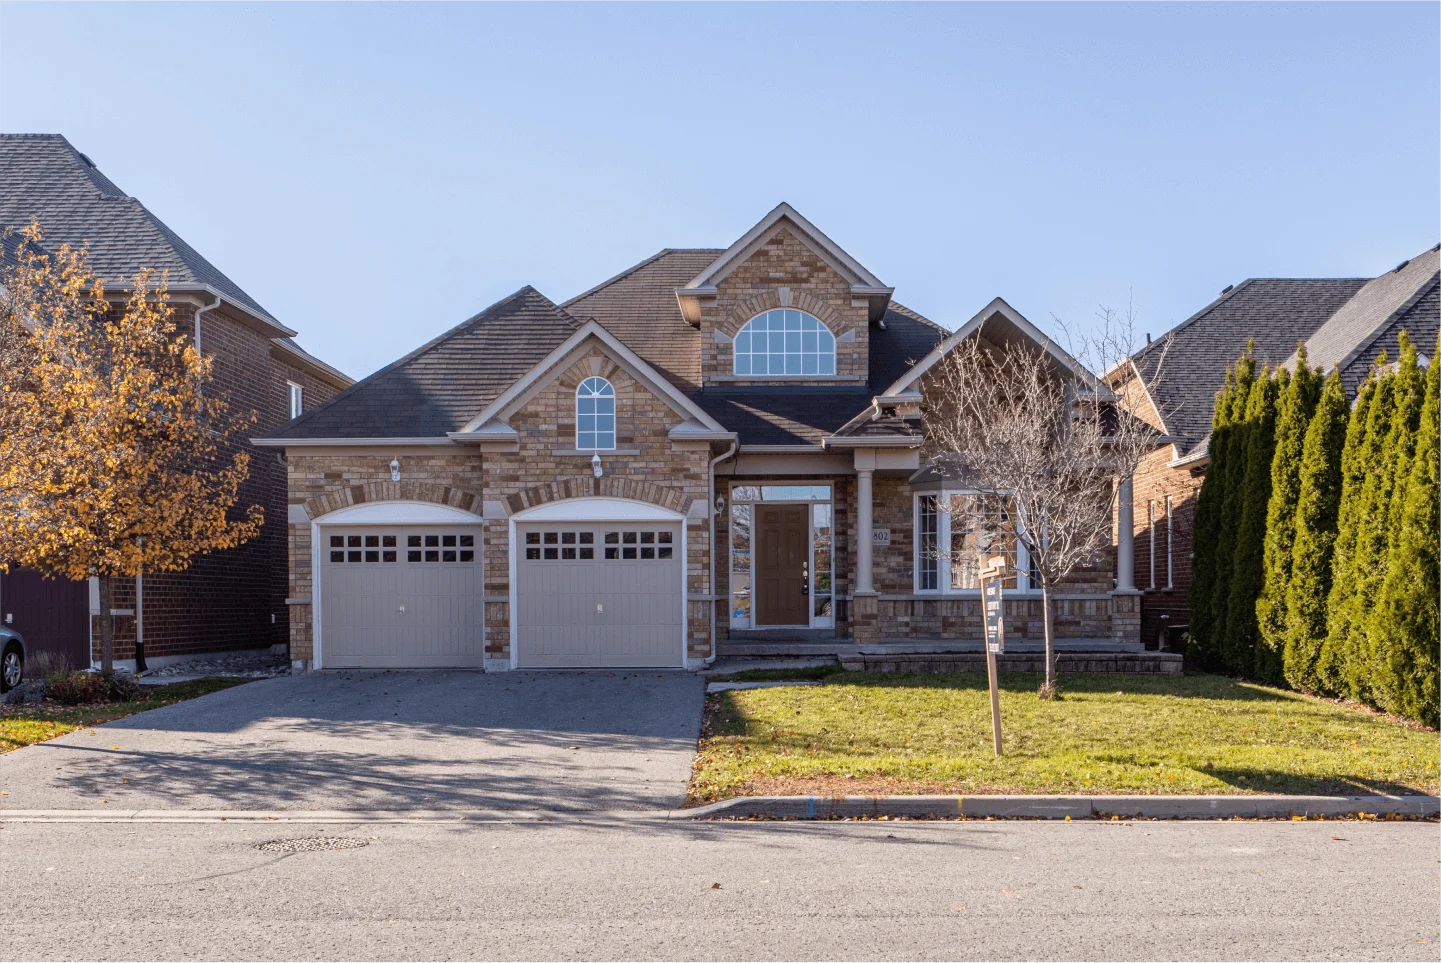
These buyers were looking at three-bedroom, two-bath homes around $820,000 in Simi Valley. The homes that fit their search were competitive, and they kept losing out.
Then their agent found a different opportunity: a four-bedroom, two-bath home with a bigger lot, listed at $880,000. It had been on the market longer and offered more room for the buyers’ long-term plans.
The higher price deserved a closer look. Before ruling it out, we needed to understand the monthly payment, cash required and financing options.
How the seller credit helped
The buyers negotiated a $30,000 seller credit. I showed them how seller funds could be used toward a permanent mortgage rate buydown, and the buyers, their agent and I worked through the plan together.
Their agent found the home and handled the real estate side. My role was to evaluate the financing and explain how the seller credit could affect the numbers.
That opened up another option beyond continuing to compete for the same smaller homes.
Watch me walk through the seller-credit strategy and the numbers buyers should compare.
What a permanent rate buydown does
A permanent rate buydown uses an upfront cost to obtain a lower mortgage interest rate. When the seller agrees to contribute toward that cost, the credit can help fund the buydown, subject to the loan’s requirements.
In this example, the financing used a permanent buydown on a fixed-rate loan. The reduced interest rate applied for the loan’s term, rather than providing a payment subsidy that ended after an introductory period.
A fixed interest rate doesn’t mean every part of the housing payment stays fixed. Property taxes, homeowners insurance and other costs can still change.
Seller credit or price reduction?
Both are worth comparing.
A lower purchase price can reduce the amount a buyer needs to borrow. A seller credit can help pay eligible closing costs, including the cost of a rate buydown when permitted.
The better choice depends on your priorities and the loan options available. You might want to preserve cash, focus on the monthly payment, or consider the total cost over the time you expect to keep the loan.
There’s also a tradeoff: money used for a buydown might otherwise be available for other eligible closing costs or a different negotiated offer. I want buyers to see those choices side by side before deciding.
Compare the full cost
When looking at a higher-priced home with a seller credit, these are the numbers I want a buyer to understand:
A seller credit doesn’t automatically make a higher-priced home affordable. The comparison still has to work for your budget, qualification and plans.
Look at the financing before ruling out the home
The lesson from this Simi Valley example is that a home’s list price doesn’t tell the whole story.
The buyers’ agent identified a larger home that had been on the market longer. A negotiated seller credit gave us another way to structure the financing. Working together allowed us to evaluate an option the buyers might otherwise have passed over.
If you’re comparing homes or wondering whether a seller credit could help, start with the full numbers before making an offer. Call or text me at 949-547-6138, or email tthrush@maltesemortgage.com. We can review the property, your payment target and the financing options together.
Tyler Thrush | Maltese Mortgage
Mortgage Broker and Retired Firefighter
NMLS #304934 | Company NMLS #1275835
Client details have been withheld for privacy. This historical example is for education and is not a current loan offer or commitment to lend. Seller credits, eligible uses and limits depend on the loan program, lender requirements and transaction. Rates, costs, qualification and results vary.
